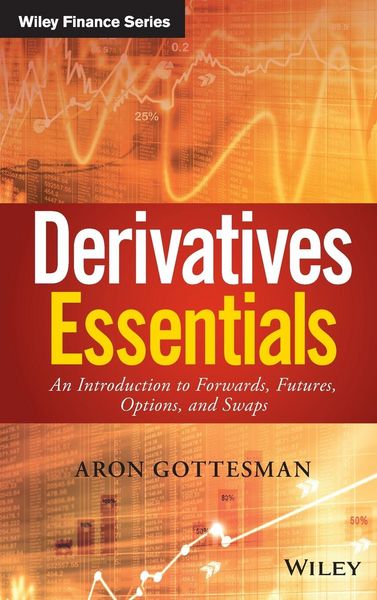
Derivatives Essentials An Introduction to Forwards, Futures, Options and Swaps
69,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Gebundene Ausgabe
Erscheinungsdatum
01.07.2016
Verlag
John Wiley & SonsSeitenzahl
352
Maße (L/B/H)
23,5/15,7/2,3 cm
Gewicht
663 g
Auflage
1. Auflage
Sprache
Englisch
ISBN
978-1-119-16349-7
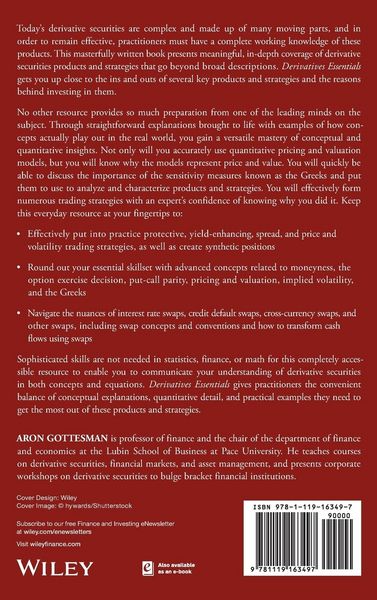
Derivatives Essentials is an accessible, yet detailed guide to derivative securities. With an emphasis on mechanisms over formulas, this book promotes a greater understanding of the topic in a straightforward manner, using plain-English explanations. Mathematics are included, but the focus is on comprehension and the issues that matter most to practitioners--including the rights and obligations, terms and conventions, opportunities and exposures, trading, motivation, sensitivities, pricing, and valuation of each product. Coverage includes forwards, futures, options, swaps, and related products and trading strategies, with practical examples that demonstrate each concept in action. The companion website provides Excel files that illustrate pricing, valuation, sensitivities, and strategies discussed in the book, and practice and assessment questions for each chapter allow you to reinforce your learning and gauge the depth of your understanding.
Derivative securities are a complex topic with many "moving parts," but practitioners must possess a full working knowledge of these products to use them effectively. This book promotes a truly internalized understanding rather than rote memorization or strict quantitation, with clear explanations and true-to-life examples.
* Understand the concepts behind derivative securities
* Delve into the nature, pricing, and offset of sensitivities
* Learn how different products are priced and valued
* Examine trading strategies and practical examples for each product
Pricing and valuation is important, but understanding the fundamental nature of each product is critical--it gives you the power to wield them more effectively, and exploit their natural behaviors to achieve both short- and long-term market goals. Derivatives Essentials provides the clarity and practical perspective you need to master the effective use of derivative securities products.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice